Most doctors I meet aren’t bad with money. They’re just doing things in the wrong order.
They max out a 401(k) while a credit card charges them 24%. They buy the house before they own any disability insurance. Each move can make sense on its own. The order is what gets people hurt.
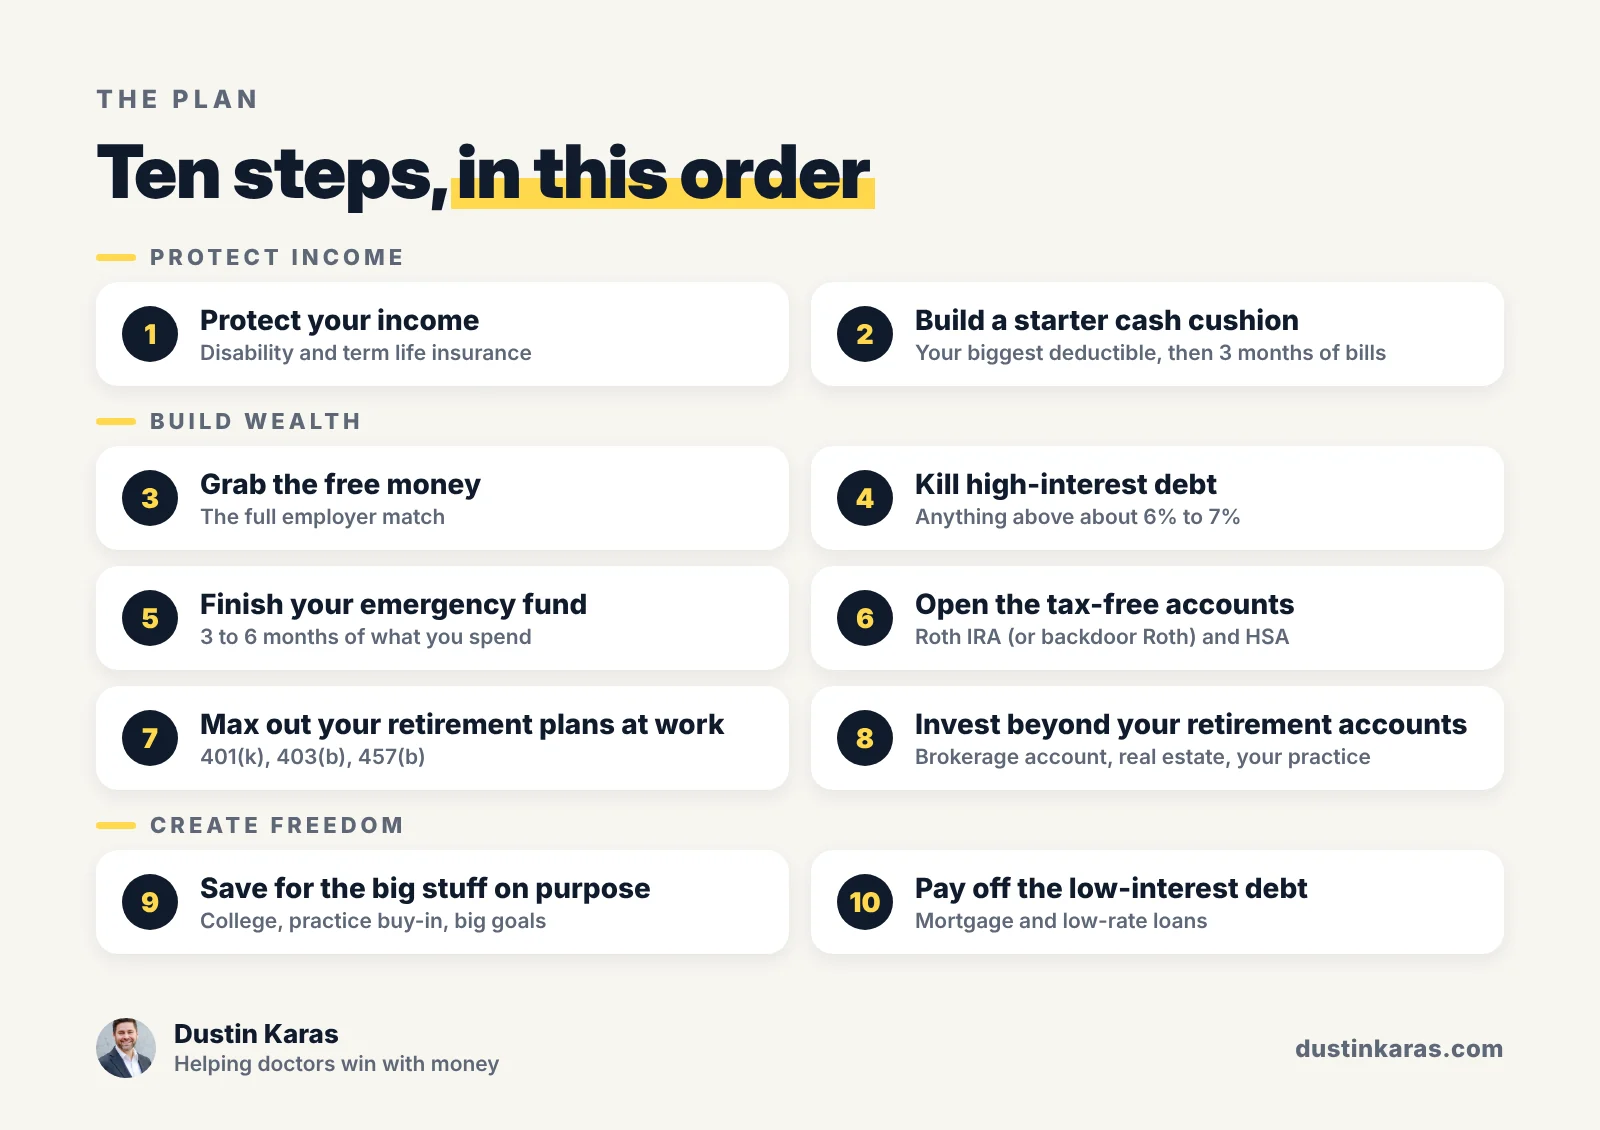
So this is the order I’d follow. Ten steps, top to bottom. Some of them overlap, and that’s fine. Just don’t jump to step 8 while step 1 is still wide open.
Quick note on me: I’m not a doctor. I’ve spent my career working around them, and my team at Pattern has helped more than 50,000 doctors understand their disability and life insurance options. I first wrote this plan as a series for my MoneyRx newsletter. This version is shorter and has 2026 numbers.
The 10 steps
- Protect your income
- Build a starter cash cushion
- Grab the free money
- Kill high-interest debt
- Finish your emergency fund
- Open the tax-free accounts
- Max out your retirement plans at work
- Invest beyond your retirement accounts
- Save for the big stuff on purpose
- Pay off the low-interest debt
Steps 1 to 3 are right below. Steps 4 to 10 unlock free with your email.
1. Protect your income
Before you invest a dollar, protect the thing that earns all the dollars.
For most doctors, that’s your ability to work. The average physician earned $386,000 in 2025. Over a 30-year career, that’s more than $11 million. You’d never leave an $11 million asset uninsured on purpose. A lot of residents do it by accident.
- Disability insurance pays you a monthly benefit if an illness or injury keeps you from working, as your policy defines it. Look for a true own-occupation definition. In plain English, the policy asks whether you can do your specialty, not whether you could do any job at all. The exact wording varies, so read yours.
- Your plan at work is a start, not the finish. Group plans usually cover less, often use a stricter definition of disability, and usually don’t go with you when you leave.
- Term life insurance matters once someone depends on your paycheck. A spouse, kids, a co-signed loan. If nobody needs your income yet, you may not need it yet.
Your price depends partly on your age and health when you apply. That’s why I tell residents to start early. You’ll probably never be younger or healthier than you are today.
This is the part I know best. For the full rundown, read my guide to disability insurance.
2. Build a starter cash cushion
An emergency fund isn’t exciting. It’s just what keeps a dead car battery or a surprise bill off your credit card.
- First, save enough to cover your biggest deductible. Health, auto, or home, whichever is highest.
- Then build up to three months of must-pay bills: housing, food, utilities, transportation, and minimum loan payments.
There’s a doctor reason for this too. Most long-term disability policies have a waiting period, often 90 days, before benefits start. This cash is what pays the bills during the wait.
3. Grab the free money
If your employer matches your 401(k) or 403(b), put in at least enough to get the full match.
A 100% match adds a dollar for every dollar you put in. Nothing else on this list comes close.
- Check the vesting schedule. Some matches only become yours after you’ve stayed a few years.
- Have an HSA? Put in at least enough to cover the medical bills you expect this year. If your employer adds money to it, make sure you’re set up to get it.
Notice what I didn’t say. I didn’t say max out your 401(k). Early in your career, that can wait. The match can’t.
4. Kill high-interest debt
A big income won’t make you wealthy if a chunk of it goes to interest.
- Credit cards and personal loans. If the rate is above about 6% or 7%, go after it hard.
- High-rate private student loans. Same idea. Pay them down fast, or shop for a lower rate.
- Federal student loans are a different story. If you’re working toward Public Service Loan Forgiveness (PSLF), paying extra usually just shrinks the amount that would have been forgiven.
Be careful about refinancing federal loans into a private loan. Once you do, you lose PSLF and the other federal protections for good.
The federal rules changed a lot in 2026. A court ended the SAVE plan in March, and a new plan called the Repayment Assistance Plan (RAP) opened July 1. Check StudentAid.gov before you pick a strategy.
5. Finish your emergency fund
Now take that starter cushion and grow it to three to six months of what you actually spend. Not just the must-pay bills. Everything.
- Keep it in a high-yield savings account, where it’s easy to reach but not too easy.
- Lean toward six months, or more, if your income bounces around. Locums, 1099 work, a new practice, or one income for the whole family.
This money isn’t an investment. Its job is to keep you from doing something desperate in a bad month, like selling investments when they’re down.
6. Open the tax-free accounts
Your base is solid. Next come the two accounts where your money can grow and come out tax-free.
Roth IRA
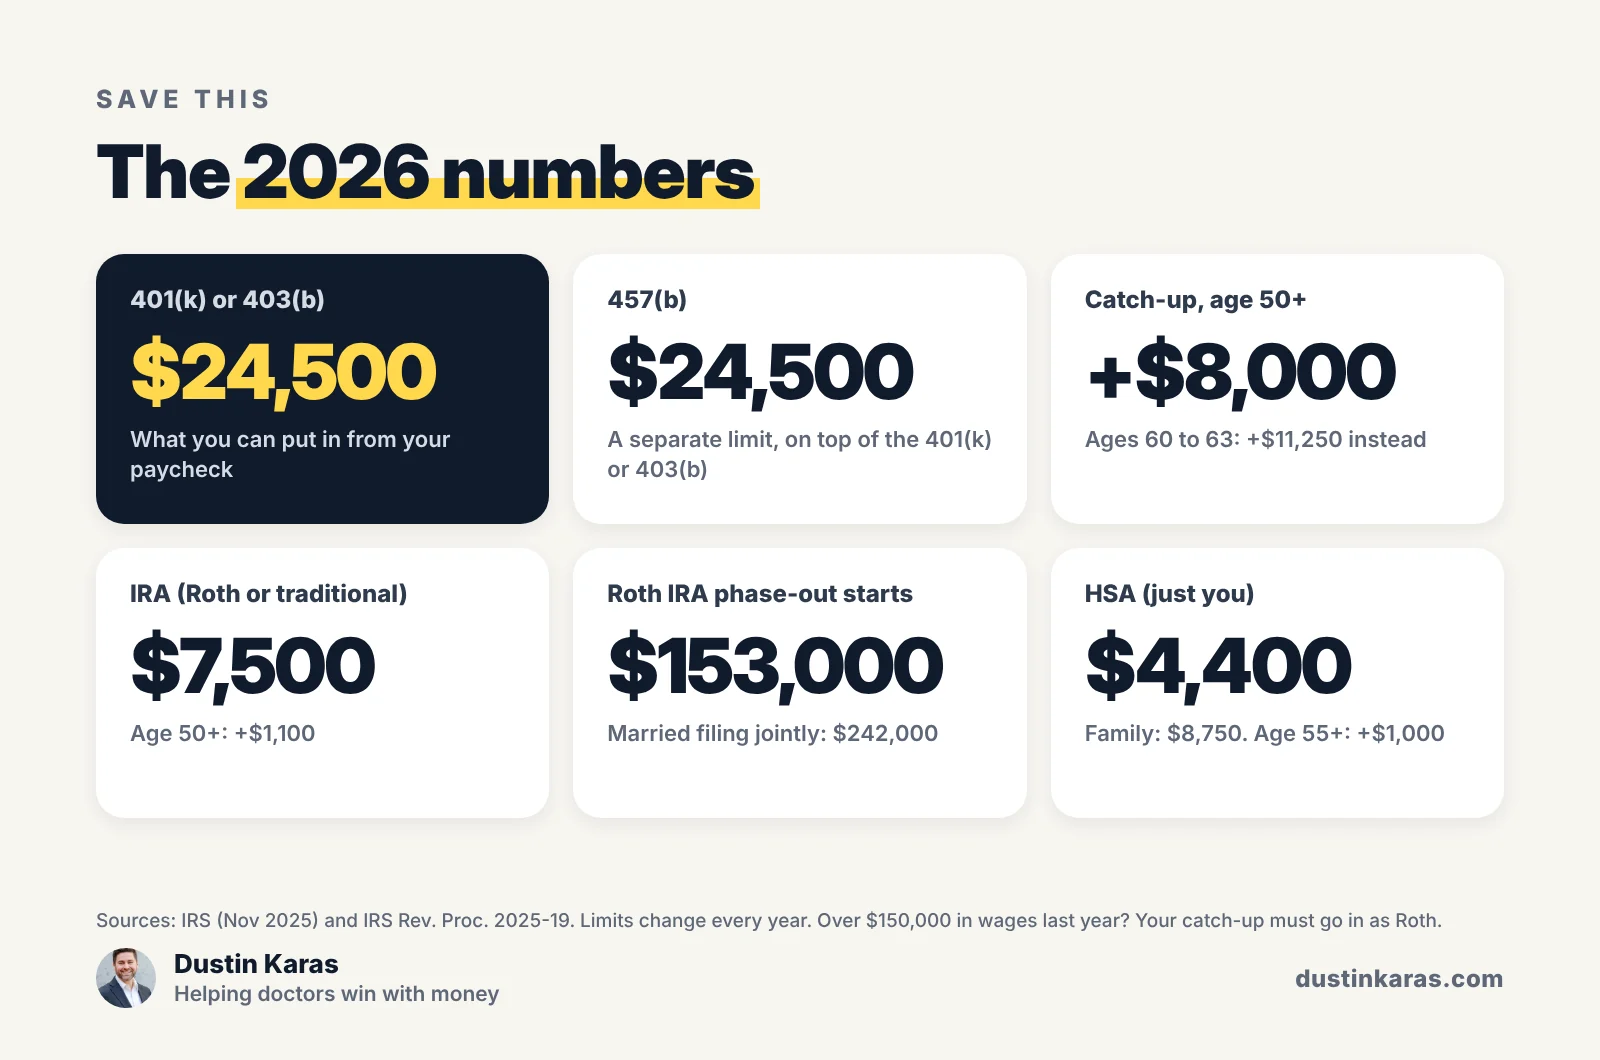
In 2026 you can put in up to $7,500, or $8,600 if you’re 50 or older. The money grows tax-free, and you can take it out tax-free in retirement.
Residents and fellows usually earn under the income limit, so a regular Roth IRA is easy. Do it while you can.
Once you earn more, you get phased out. In 2026 that starts at $153,000 of income if you’re single, or $242,000 if you’re married filing jointly. Above that, most doctors use a backdoor Roth: put money into a traditional IRA, then convert it to a Roth.
One warning. If you have pre-tax money in a traditional, SEP, or SIMPLE IRA at the end of the year you convert, the backdoor can create a surprise tax bill. It’s called the pro-rata rule. Get help the first time you do it.
HSA
If you have a health plan that qualifies for an HSA, try to max it out. For 2026 that’s $4,400 for just you, or $8,750 for a family. Add $1,000 if you’re 55 or older.
An HSA is tax-free going in, tax-free while it grows, and tax-free coming out for medical bills. If you can, pay small medical bills from checking and let the HSA money stay invested.
7. Max out your retirement plans at work
Now fill up the big retirement accounts at work. Pre-tax contributions lower your taxable income today.
- 401(k) or 403(b): up to $24,500 in 2026. If you’re 50 or older, add $8,000. If you’re 60 to 63, add $11,250 instead.
- Earned more than $150,000 in wages at that job last year? Starting in 2026, your catch-up has to go in as Roth, after tax. If your plan has no Roth option, you can’t make a catch-up there.
- Got a 457(b) too? A lot of hospitals offer one next to the 403(b). It has its own separate $24,500 limit, so you may be able to fill both.
- Careful with a non-governmental 457(b). Legally, that money is still your employer’s until it pays you. If the employer runs into money trouble, creditors can go after it. Read the plan rules before you go all in.
- Self-employed or 1099? Look at a solo 401(k) or a SEP IRA.
The sooner money goes in, the longer it has to grow.
8. Invest beyond your retirement accounts
Once you’re filling the tax-advantaged accounts every year, extra savings can go to work somewhere else.
- A regular brokerage account. No contribution limit and no age rules for taking money out. Simple and low-cost is a good default.
- Real estate. It can add income and spread out your risk. It can also become a second job. Go in with your eyes open.
- Own a practice? This may be where investing in your own business makes sense.
This is the step most doctors want to start with. It works a lot better as step 8.
9. Save for the big stuff on purpose
Big expenses are coming whether you plan for them or not. Planning just means you pay cash instead of interest.
- Kids’ college: a 529 plan grows tax-free when you use it for school. Many states give you a tax break for using theirs.
- Practice buy-in: if a partnership is in your future, start saving years ahead.
- The fun stuff: a vacation home, a sabbatical, a year of working part-time. Put them on the plan and fund them like bills.
10. Pay off the low-interest debt
By now, your mortgage and maybe some low-rate student loans are the only debt left. This step is last on purpose.
On paper, paying off a 3% mortgage early usually loses to investing. I won’t pretend otherwise. But owning your home free and clear changes how much you need to earn. Lower bills mean more choices. Cut back to part-time, or take the job you love that pays less.
Money won’t give your life meaning. It can give you options. That’s what all ten steps are for.
Where to start
Find the first step you haven’t finished. That’s your step. Ignore the rest for now.
Here’s the whole plan on one page. Save it.
The order matters more than the speed.